8 Questions You’ve Been Afraid to Ask Your Financial Advisor
Buying a home may be one of the biggest financial decisions you’ll ever make, but it’s only one piece of your overall financial picture. Mortgages, investments, retirement, real estate, debt, taxes and even the daily headlines can all influence the decisions we make with our money.
So, we decided to ask the experts some of the questions many of us have probably wondered about—but may not always ask.
We turned to Tim and Max of Journey Financial, an independent financial planning firm in Jefferson, Iowa, and asked them eight intentionally provocative questions about money, investing and real estate.
Their answers may challenge some of the conventional financial wisdom you’ve heard.
PROmetro Realty is not a financial advisor and does not provide financial, investment, tax or legal advice. The following responses are provided by Journey Financial for general educational purposes.
1. Is paying off my mortgage early actually a bad financial decision?
Being debt-free sounds like an obvious financial goal. But if someone has a low-interest mortgage, could putting extra money toward the house actually leave them worse off financially?
Tim looks first at the interest rate, the client's age and what that money could potentially earn elsewhere. For homeowners fortunate enough to have a mortgage below 3%, he points out that even some cash investments may currently earn more than the cost of their mortgage.
But Tim doesn't think the decision should be based entirely on the numbers:
“Since there is still risk involved, I often ask clients to do what gives them peace of mind.”
He'd also prioritize paying off credit-card debt and loans on depreciating assets such as cars, campers and boats before aggressively paying down a mortgage.
Max: “Not necessarily. I don't think paying off your mortgage early is ever automatically a ‘bad’ decision, but it may not always be the most financially efficient decision. If you have a mortgage at 3% and you're putting an extra $2,000 a month toward it, you have to consider what else you could be doing with that $2,000. Could you be contributing more to a 401(k), funding Roth accounts, investing in a brokerage account, or building up cash reserves? Over a long period of time, those alternatives could potentially create more wealth than the interest you're saving on a low-rate mortgage.
But there's also a psychological side to it. Some people place a huge value on being debt-free, especially going into retirement. That's worth something too. So, I don't think the question is simply, ‘Should I pay off my mortgage?’ It's, ‘What's the best use of my next dollar?’ Sometimes that's the mortgage. Sometimes it's investing. Or maybe it's a combination of both.”
2. If the stock market crashed tomorrow, what would you tell me to do?
Market downturns can make even long-term investors question their plans. What should someone do when the market drops significantly—and what should they have done before it happened?
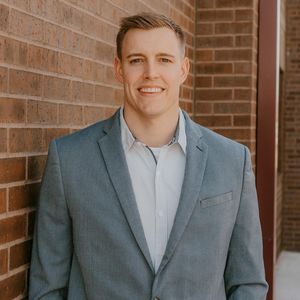
Max Neese, Certified Financial Planner
Max: “Probably nothing dramatically different from what we were already planning to do.
The more important conversation actually happens before the market crashes. If money is invested in equities that you're going to need six months from now, we probably made a mistake before the downturn ever happened. We want clients to have the appropriate amount of cash and more conservative investments available for their shorter-term needs so that when the stock market does go through a bad period, we're not forced to sell investments at the worst possible time.
For someone who is still accumulating and investing every month, a downturn can actually create opportunities because they're buying at lower prices. For retirees, it's more about having an income strategy that doesn't force them to sell stocks every time the market is down. Market declines aren't fun, but they're also not unusual. The plan should anticipate that they're going to happen.”
Tim starts with another question: Why did the market crash? Was it a war, pandemic or another unpredictable event? He notes that markets can have a knee-jerk reaction to major events, but the longer-term question is whether the event actually changes the earnings potential of the companies someone owns. If it doesn't, his advice may simply be to stay invested.
And preparation matters:
“We invest our clients' portfolios in such a way that if the market crashed, they have other assets to help them ‘weather the storm’...that is planning before the downturn happens.”
3. My house has appreciated more than my investments. Why shouldn’t I put more of my money into real estate?
If real estate has worked well for someone, why not buy a rental property, land or another home instead of investing more money in the market?
Tim: “We like real estate a lot.”
He sees real estate as another potential source of income, particularly in retirement. Someone who enters retirement with several streams of income—retirement plans, pensions, rental income, Social Security and investment income—may have greater financial flexibility.
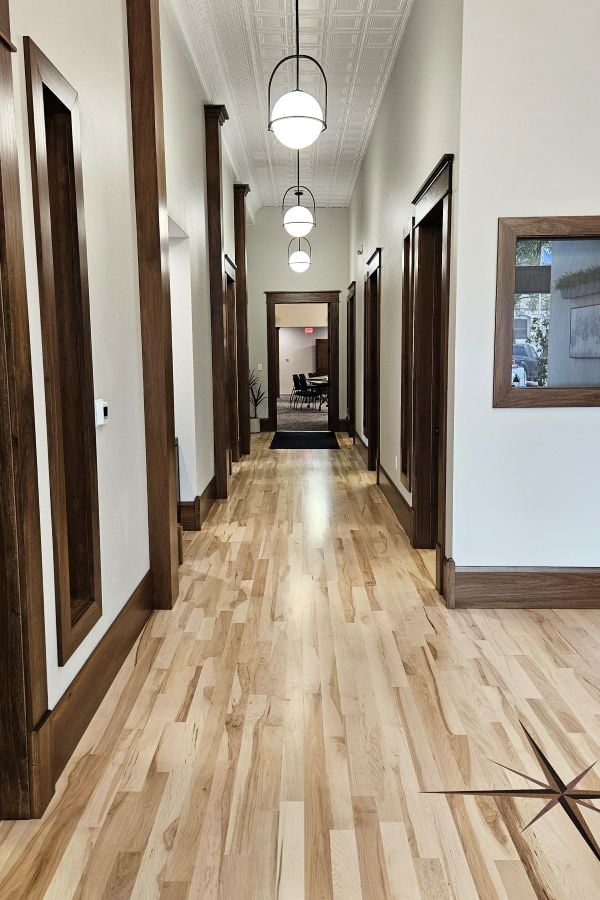
Journey Financial Offices
“Real estate is just another diversifier, which decreases risk.”
Max sees plenty of value in real estate as well, but cautions against directly comparing the appreciation of a home to the return on an investment account.
“You absolutely can invest more in real estate. Real estate has created a lot of wealth for people. I just wouldn't look at the appreciation of your house and compare it directly to the return on an investment account. They're very different investments.
Real estate can provide appreciation, rental income and leverage, but it also comes with property taxes, insurance, maintenance, transaction costs and potentially a lot more work. It's also much less liquid. If you suddenly need $50,000, you can't sell the kitchen out of your rental property.
The other consideration is diversification. I like real estate. I just don't think it has to be an either/or decision between real estate and traditional investments. For a lot of people, owning both creates a stronger overall financial picture.”
4. If I inherited $500,000 tomorrow, what’s the first thing you’d tell me NOT to do?
Receiving a large inheritance can suddenly create financial choices someone has never had to make before. What's the biggest mistake?
Tim's advice is pretty direct:
“Don't make hasty decisions. Don't go buy a boat, a Corvette, a lake house, etc. in the first year.”
He'd also be careful about where the advice comes from:
“Don't take advice from your brother-in-law or one of your coffee buddies. They generally don't know what they are talking about.”
Max also recommends resisting the urge to immediately put the money to work.
“Don't feel like you need to make a decision immediately. You don't have to invest it tomorrow. You don't have to pay off your mortgage tomorrow. You don't need to buy a new house or car. Put the money somewhere safe and give yourself some time, especially given that this can be an emotional time if a loved one has passed.
Then I would step back and look at your entire financial situation. Do you have debt? Are you saving enough for retirement? Do you have kids that you're trying to help with college? Are there tax consequences associated with what you inherited? What are your goals over the next 5, 10, or 20+ years? The answer could end up being five different things. Maybe some gets invested, some pays down debt, some goes toward a major purchase and some stays in cash.
The biggest mistake would probably be treating $500,000 as money that needs to be put to work immediately before you've figured out what you actually want it to accomplish.”
5. What do financially successful people do with their money that the rest of us misunderstand?
Are wealthy people using investment strategies the rest of us don't know about?
According to Max, it's usually much less exciting than people imagine.
“I think one of the biggest misconceptions is that people who have accumulated a lot of wealth must have done something extraordinary with their money. Most of the time, it's actually pretty boring. They consistently save and invest, they own good investments or businesses for long periods of time, and they let compounding do the heavy lifting. They aren't constantly chasing the next hot investment or trying to get rich overnight.
Building wealth usually doesn't happen overnight. It's doing the right things over and over again for 20, 30, or 40 years. Saving when the market is up, continuing to save when the market is down, and giving those dollars enough time to compound. I think people underestimate just how powerful consistency and time can be.
You don't need to hit a bunch of home runs. A lot of financially successful people simply made good, relatively boring decisions for a really long time.”
Tim sees another common trait: delaying gratification.
“The most successful investors are able to delay the gratification of having stuff. They won't go into needless debt just to have a fancy car or go on expensive trips. Instead they live within their means and ‘pay themselves first’ by investing in retirement accounts.”
And for many people, he says, building wealth really is that straightforward:
“Most of our clients got to where they are by systematically investing on a monthly basis.”
6. Are there investments you would NEVER recommend to your own family?
Some investments can sound extremely attractive on the surface. What types of investments or opportunities make a financial advisor particularly cautious?
Tim points to investments with long surrender periods as something he approaches cautiously, including some annuities.
He'd also be wary of companies that aren't profitable or have slow earnings growth, along with investment opportunities promising returns that simply seem too good to be true.
Max looks for several additional warning signs:
“I'm always cautious anytime an investment is being presented as having high returns with very little risk. Those two things generally don't go together.
I'd also be cautious with anything that's extremely complicated, illiquid, has very high fees, or where someone can't clearly explain how the investment actually makes money. That doesn't mean every alternative or complicated investment is bad. There are legitimate private investments, real estate investments, structured investments and other strategies that can make sense.
But the more complicated something gets, the more important it is to understand exactly what you're buying. One of my biggest warning signs is urgency. If somebody is telling you this is a once-in-a-lifetime opportunity, that's usually when I'd want you to slow down the most.”
7. What financial advice sounds smart but is actually terrible advice?
There's no shortage of financial advice from family, friends, social media and the internet. What commonly repeated advice deserves to be challenged?
Max's answer is simple: “Any financial advice that starts with ‘always’ or ‘never'.”
As examples of the kind of blanket advice he cautions against, he points to statements like:
“Always pay off your mortgage.”
“Never carry debt.”
“Always max out your 401(k).”
“Always buy real estate.”
“There might be situations where every one of those recommendations is correct, but none of them should automatically apply to everyone. Personal finance is personal. I'd rather understand someone's entire financial picture and then make the decision than start with a rule and try to make their situation fit it.”
Tim points to another piece of conventional wisdom he frequently hears: Investing in the stock market is risky and you'll lose all your money.
“Yes, some stocks are very risky because they are not profitable,” he says. “But profitable companies with good earnings growth can be financially rewarding over time.”
8. Everything feels expensive and uncertain right now. Should I be doing something differently with my money?
Higher borrowing costs, everyday expenses, market swings and uncertainty around the economy and world events can make it feel like a bad time to make any major financial move.
Should uncertainty actually change your plans?
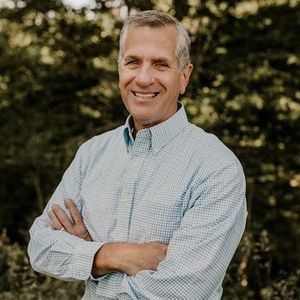
Tim Heisterkamp, Certified Financial Planner
Tim's advice:
“Reacting to headlines usually is not a good idea either way: bad or good headlines.”
“If an investor has a plan and lives within their means, then most of the time, I would tell them to keep doing what they are doing, in spite of the headlines!”
He does make an important distinction. A major change in your own life may matter considerably more than what's happening in the news.
“Personal events like losing a job or the death of a spouse would be reasons to stop and reevaluate.”
Max points out that uncertainty itself is nothing new.
“I think uncertainty feels unique when you're living through it, but there's almost always something to be worried about. We've had recessions, wars, inflation, elections, banking crises, pandemics, interest-rate changes and market crashes. That doesn't mean you ignore what's happening. Higher interest rates absolutely matter if you're buying a house. Inflation matters when we're projecting retirement spending. Tax law changes can create planning opportunities. We should adjust when the facts change.
What I wouldn't do is completely change a long-term financial plan or investment strategy every time the headlines get uncomfortable. I'd focus on the things you can actually control like how much you're saving, how much you're spending, how your investments are allocated, your taxes, your debt and whether you have enough liquidity for what's coming in the next few years.”
About Journey Financial
Journey Financial is an independent financial planning practice based in Jefferson, Iowa, helping clients with investments, retirement planning, tax planning, estate planning, insurance and employer retirement plans. Their approach focuses on looking at the entire financial picture—not simply managing investments—and helping clients understand the decisions they’re making along the way.
As Tim puts it:
“We feel clients who understand their finances have a higher degree of peace of mind.”
Learn more about Journey Financial.
Your Home Is Part of the Financial Picture
Buying or selling a home isn't just a real estate decision—it's often one of the biggest financial decisions you'll make. Whether you're buying your first home, considering a move, investing in real estate, or thinking about how your home fits into your long-term plans, having the right professionals in your corner can make a big difference.
At PROmetro Realty, we help buyers and sellers throughout Central Iowa make informed real estate decisions with experienced, straightforward guidance.
Thinking about buying or selling? Get started with PROmetro Realty.
This article is provided for general informational and educational purposes only. PROmetro Realty is not a financial advisor and does not provide financial, investment, tax or legal advice. Readers should consult an appropriately qualified professional regarding their individual circumstances.
Check out this article next